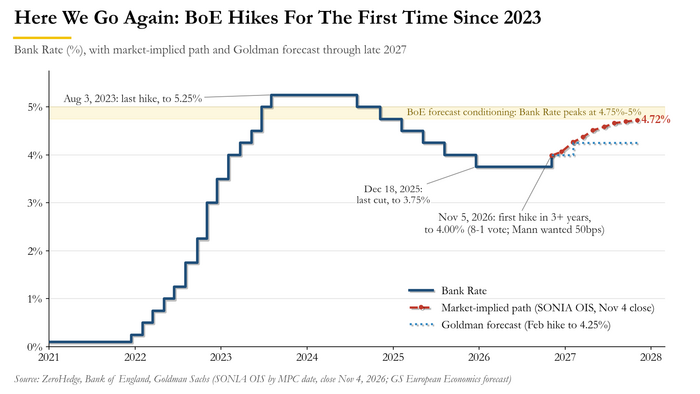
For the first time in 1,190 days, the Bank of England has raised interest rates.On Thursday the BoE's Monetary Policy Committee voted 8-1 to lift Bank Rate by 25bps to 4.00%, the first hike since August 3, 2023, when the BoE topped out at 5.
25%. And the lone dissenter was no dove: external member Catherine Mann wanted a half-point move to 4.25%.
Put differently, not a single one of the nine MPC members voted to keep rates on hold, which is a little more hawkish than consensus: Goldman and JPMorgan both expected a 7-2 vote (Goldman's STIR desk had Swati Dhingra and Alan Taylor as the holdouts), while Deutsche Bank's UK economists were looking for a 6-3 split.Even the doves came along, if grudgingly. Alan Taylor, one of the most dovish members of the committee, called it "a risk management, 'one-for-now' insurance hike," while Governor Andrew Bailey, in his own written paragraph, went a step further:"I can see the argument for a further increase in rates and thereafter taking a more conditional approach...
Today's increase shouldn't be seen as the first in an inevitable long sequence of hikes. But, unless the conflict in the Middle East is resolved, neither does it seem to be the last increase."In other words, December is live, and traders took the hint: according to Bloomberg, the market now prices roughly a 50% chance of another quarter-point hike next month, and almost three more 25bp hikes by the end of 2027.
Two-year gilt yields rose 3bps to 4.77%, and the pound steadied around $1.3472.
Regular readers won't be surprised. Back in March, just weeks into the Iran war, a 9-0 "hawkish hold" sent UK gilt yields exploding higher on a surprise BoE rate-hike threat, with 2Y yields jumping 30bps in a day. And in September, when the BoE held at 3.
75% in a 6-3 vote (Mann, Huw Pill and Megan Greene already voting to hike), we warned that the decision would "leave a near-term hike firmly in play," so we'll allow ourselves a modest victory lap.BoE Hold Masks A Sharper Bias Towards TighteningThe Bank of England held the Bank Rate at 3.75% in a 6–3 vote, as expected, but shifted closer to further tightening.
Energy prices have risen sharply since July, lifting the Bank’s early-2027 inflation forecast above 4%, while…— zerohedge (@zerohedge) September 17, 2026With today's move, the BoE joins a club that is getting crowded: the Fed hiked for the first time since July 2023 back in September, the RBA has been hiking into a housing slump, and with Euro area headline inflation at a 3-year high of 4.0%, the ECB probably isn't far behind. Which, as Goldman put it last weekend, makes central banks the market's last "source of calm"...
"good luck."From 3.2% To 4.
9% In One ReportThe reason for the hawkish turn is in the BoE's new November Monetary Policy Report. CPI inflation, which was 3.5% in September, is now projected to peak at 4.
9% in Q2 2027, the highest since September 2023. Just three months ago, in the July forecasts, the BoE saw inflation peaking at a much more benign 3.2%.
That's quite a revision for one quarter, even by central bank forecasting standards.Most of the overshoot is mechanical: household utility bills and motor fuel accounted for around 60% of September's overshoot of the 2% target, and it's about to get worse. The Ofgem price cap is expected to rise to around £2,150 in Q1 2027 from £1,723 in Q4, a ~25% jump in household energy bills in January, with another increase likely in April.
Direct energy effects alone are projected to add around 1.4 percentage points to CPI in Q1.The BoE admits there is "limited evidence" so far of second-round effects in wages and prices, but it suspects that is a timing issue: firms have been shielded by "hedging and long-term fixed price contracts," and the MPC fears pass-through will come once those expire.
And the scenarios are not pretty. In the adverse case of repeated escalations in the Iran conflict, CPI hits 6.2% in Q3 2027; in the "weaker demand" scenario, inflation instead collapses to 1.
2%, which would, ironically, require rate cuts.Meanwhile the economy has been more resilient than the BoE expected (or maybe just more resilient than it wanted): the 2026 GDP forecast was upgraded to 1.6% from 1.
1%, and 2027 to 1.3% from 1.1%, although 2028 was cut to 1.
2% from 1.7% on the assumption that the energy shock lingers. The MPC's verdict: while "policy was still restrictive" before Thursday's hike, "it was less clear that this would impart sufficiently disinflationary pressure to bring inflation back to target in a timely manner.
"Bailey had been laying the groundwork for weeks. Here was the Governor a month ago:*BAILEY: INFLATION RISKS RISE LONGER HIGH ENERGY PRICES PERSIST*BAILEY: EVIDENCE OF INFLATION PASS-THROUGH SUBDUED AT MOMENT— zerohedge (@zerohedge) October 8, 2026Hiking Into An Oil CrashThere is just one small problem with the BoE's inflation math: the oil price it's built on no longer exists.The MPR's projections are conditioned on energy futures averaged over the 15 working days to October 27, during which front-month Brent averaged $108 per barrel, around 70% above pre-war levels, while UK gas futures over the forecast horizon were some 120% above their pre-conflict levels.
Then the US midterms happened. As we detailed yesterday, crude crashed as the "Blue-nami" sparked market chaos, with Brent plunging 8.7% on Wednesday to close at $94.
62, beneath $100 for the first time since September, after Vance boldly admitted that "the reason we lost is the war." Physical markets were already flashing the same signal, flipping from bidding war to fire sale as Gulf barrels flood back.That's roughly 12% below the oil price the BoE plugged into its forecast (napkin math, and Brent is a moving target).
Deutsche Bank's Jim Reid noted in his Early Morning Reid that the oil slide "significantly dampen[ed] fears over inflation," and the market agreed: the Euro 1-year inflation swap plunged 25.9bps on the day to a two-month low of 3.10%.
JPMorgan's Federico Manicardi was even more explicit in his morning briefing (available to pro subs), writing that the market reads the Democratic sweep as a "flatter geopolitical risk curve on Iran," and that "lower Brent/Gas risk premia with the global oil balance already back in surplus (+1.4 mbd in October vs ~+1.3 mbd on avg last year) should ease pressure on central banks.
"Good news for UK households, maybe. Less so for the credibility of a forecast that was stale before it was even published. To be fair to the BoE, the MPR itself warns that inventories are thin, European gas storage is below average and a cold winter could send prices spiking again.
And Iran just rejected the latest draft proposal to end the war, so nobody should be declaring the energy shock over just yet.Goldman: One More In February, But The Market Is Getting Ahead Of ItselfSo where does Bank Rate go from here? Going into the meeting, Goldman's European economists led by Sven Jari Stehn had already pencilled in a second hike, writing in their BoE preview, "A Hike with Noncommittal Guidance" (available to pro subs), that they "now expect a second Bank Rate hike to 4.
25% in February given continued upward pressure on energy prices and the stronger recent activity and labour market figures." But there is a big caveat:"We continue to think that market pricing for over 100bp of tightening over the next year looks too high given that second-round effects into wages look contained and consumer spending growth is likely to slow over the winter."Goldman's STIR trader Daryl Li was even blunter in this morning's GS Morning note from Adam Crook (available to pro subs).
With the December, February and March meetings pricing a cumulative 36bps (down from 41bps the day before), he thinks "this pricing has more to come out with or without de-escalation, mainly because the data has been good but not exponential - we should be pricing between 0-1 hikes per quarter, not 1-2." His take on December:"With the war still unresolved, rece