It's very busy week ahead with US payrolls (Friday) and PCE (Wednesday) as the blockbuster releases. The US ISM (Thursday) will attract outsized attention given the spectacular beat on the S&P PMI last week that sent 10yr US yields +15.2bps higher on the day.
A huge move for such a report. Global inflation will also be in focus outside of the US August PCE report with flash September CPI releases across Europe (Tuesday/Wednesday) and Tokyo CPI (Friday) all due. In Asia, investors will also be watching Chinese PMIs (Wednesday), the BoJ’s Tankan survey and summary of opinions (Thursday), as well as the RBA decision (tomorrow) where the market prices in a 93% probability of a hike.
All that around month and quarter end on Wednesday.In the US, attention will increasingly turn towards Friday’s September payrolls report. Following August’s stronger-than-expected gain of 162k, DB economists expect payrolls to rise by around 45k in September (Friday), with the unemployment rate unchanged at 4.
1% and average hourly earnings growth steady at +0.3% month-on-month. Recent labor market indicators have remained reasonably firm, although some moderation after August’s strength would be consistent with a labou market that is cooling only gradually.
Ahead of Friday’s payrolls release, labor market data will begin arriving tomorrow with the August JOLTS report, before the September ADP employment release on Wednesday and weekly jobless claims on Thursday. Together, these releases should help shape last minute expectations going into the official employment report. Note that last week saw claims at 197k, a rare dip below 200k.
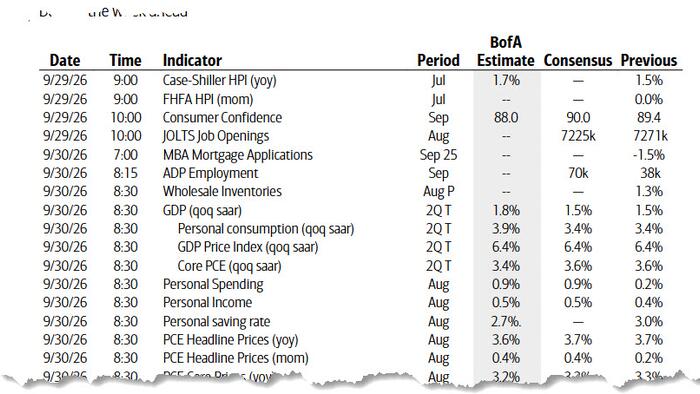
Moving onto inflation, DB economists expect the August core PCE deflator (Wednesday) to rise by +0.27% month-on-month, slightly above July’s pace. The report will be accompanied by personal income and spending data, where economists expect gains of +0.
5% and +0.6% respectively. Particular attention will be paid to the PCE release given the BEA’s annual benchmark revisions and methodology changes, which could alter the recent inflation profile and affect comparisons with previous months.
Elsewhere in the US, the Conference Board consumer confidence index (tomorrow) is expected to drop to 89.1 from 89.4, while the ISM manufacturing index (Thursday) is expected to rise to 55.
0 from 54.6. Remember the S&P composite PMI hit 58.
4 last week. We get the ISM services print next week. Wednesday’s final Q2 GDP release will also attract attention as it incorporates benchmark revisions that may reshape perceptions of recent growth trends.
As we end the quarter, note that the Atlanta Fed GDPNow is currently tracking at 5.02% for Q3.Outside the US, European inflation data will dominate the calendar.
Preliminary September CPI releases begin with Spain tomorrow, followed by Germany, France and Italy on Wednesday, before the Eurozone aggregate reading on Friday. DB economists expect Eurozone headline HICP inflation to print at 3.75% year-on-year, with core inflation at 2.
53%. In Japan, today’s BoJ minutes from the July meeting will be followed by the Q3 Tankan survey and September meeting summary of opinions on Thursday, while economists expect Friday’s Tokyo CPI report to show a further firming in underlying inflation. China’s September PMIs are due on Wednesday, while the RBA announces its latest policy decision tomorrow, where DB economists expect a 25bp rate increaseHere is a day-by-day calendar of events courtesy of DB:Monday September 28Data: US September Dallas Fed manufacturing activity, China August industrial profits, Japan August PPI servicesCentral banks: Fed's Barkin speaks, ECB's Lagarde and Pereira speak, BoE’s Ramsden speaks, BoJ minutes of the July meetingEarnings: JefferiesTuesday September 29Data: US September Conference Board consumer confidence index, Dallas Fed services activity, August JOLTS report, July FHFA house price index, UK August net consumer credit, M4, Italy July industrial sales, August PPI, Eurozone September economic confidence, Canada July GDPCentral banks: Fed's Goolsbee and Williams speak, ECB's Kazimir, Nagel, Escriva and Cipollone speak, BoE’s Taylor speaks, RBA decisionEarnings: CarnivalWednesday September 30Data: US September ADP report, MNI Chicago PMI, August PCE, personal income, spending, advance goods trade balance, wholesale inventories, China September PMIs, UK September Lloyds Business Barometer, Q2 current account balance, Japan August retail sales, industrial production, housing starts, Germany September CPI, unemployment claims rate, August import price index, retail sales, France September CPI, August PPI, consumer spending, Italy September CPI, consumer confidence, economic sentiment, manufacturing confidence, Australia August CPICentral banks: Fed's Barkin, Cook, Goolsbee and Kashkari speak, ECB's Schnabel speaksEarnings: Micron, FactsetOther: G20 Trade Ministerial in Milwaukee (through October 1)Thursday October 1Data: US September ISM index, total vehicles sales, August construction spending, initial jobless claims, Japan Q3 Tankan survey, Italy August unemployment rate, September manufacturing PMI, new car registrations, budget balance, Eurozone August unemployment rate, Canada September manufacturing PMI, Switzerland September CPICentral banks: Fed's Barkin, Collins, Schmid, Cook and Logan speak, ECB's Cipollone, Makhlouf, Lagarde, Sleijpen and Nagel speak, BoE's Bailey and Mann speak, BoJ’s summary of opinions from September meetingEarnings: NikeOther: China National Day holiday (through September 7)Friday October 2Data: US September jobs report, August factory orders, Japan September Tokyo CPI, monetary base, August jobless rate, job-to-applicant ratio, Italy August retail sales, Eurozone September CPICentral banks: ECB's Moulin, Cipollone, Vujcic and Nagel speak, BoE’s DMP surveyFinally, lookinat just the US, here is a list of the key economic data releases this week are the core PCE report on Wednesday and the employment report on Friday.
There are many speaking engagements with Fed officials this week. Monday, September 28 There are no major data releases scheduled.08:15 AM Fed Vice Chair for Supervision Michelle Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will speak about banking supervision and regulation at the 2026 Military Banking Summit in Washington, D.
C. Moderated Q&A is expected.01:25 PM Fed Governor Lisa Cook speaks: Fed Governor Lisa Cook will speak about AI and emerging technologies at the 2026 Oakland Tech Week.
Speech text is expected.01:30 PM Richmond Fed President Tom Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will participate in a fireside chat at the Working Class Insights Forum in Middleburg, Virginia. Moderated Q&A is expected.
On September 24, President Barkin said that “if inflation is not going to come down relatively quickly, then you have to look in the mirror and say inflation looks like it’s been here for a while. So maybe we should do something about it. I think that’s what happened [at the September FOMC meeting].
”Tuesday, September 29 09:00 AM Case-Shiller home price index, July (GS +0.3%, consensus +0.2%, last +0.
2%)10:00 AM Conference Board consumer confidence, September (GS 89.0, consensus 89.2, last 89.
4)10:00 AM JOLTS job openings, August (GS 7,300k, consensus 7,225k, last 7,271k): We estimate that JOLTS job openings were roughly unchanged at 7.3mn in August based on the signal from online measures of job postings from Indeed and LinkUp.11:00 AM Fed Vice Chair for Supervision Michelle Bowman speaks: Fed Vice Chair for Supervision Michelle Bowman will deliver virtual opening remarks to the Federal Reserve System Community Bank Cyber Workshop.
Speech text is expected. 12:40 PM Fed Governor Michael Barr speaks: Fed Governor Michael Barr will speak about the economic outlook at the Detroit Economic Club. Speech text and moderated Q&A with audience are expected.
On September 23, Governor Barr noted that “further policy adjustments